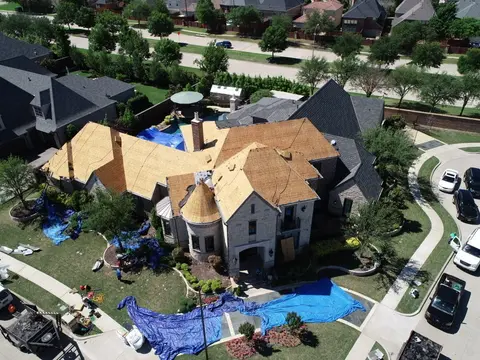
Hail-Damaged Roof Replacement in Forney: Who to Call
 By Chris Grimes, owner of Verde RoofingPublished October 31, 2026 · 9 min read
In short
Verde Roofing, a locally owned roofer based in Plano, replaces hail-damaged roofs in Forney and the rest of Kaufman County. Owner Chris Grimes inspects the roof with you, photographs what he finds, meets your adjuster on site and gives you a free written estimate; call or text (214) 687-1951, 24/7. Verde is an NTRCA Accredited Member. With any roofer, check that the deductible appears on the contract as an amount you pay.
Key takeaways
- Hail damage does not always mean a new roof; an inspection with photos should show whether the damage is a few shingles or spread across several slopes.
- You file and own the insurance claim; under Texas Insurance Code §4102.163 a roofer may not act as a public adjuster on a property it is working on.
- The Texas Department of Insurance says an insurer has 15 business days to acknowledge a claim and must pay within five business days after agreeing to pay.
- Texas Business and Commerce Code §27.02 makes it a Class B misdemeanor for a contractor to pay, waive, absorb or rebate your deductible without the insurer's consent.
- In an HOA subdivision, get shingle style and color approved before materials are ordered.
A hailstorm crosses Kaufman County, and by the next weekend there are yard signs on every other lawn and strangers with clipboards working the cul-de-sacs. If you own a home in Forney, you are probably asking two things at once: is my roof actually damaged, and who can I trust to replace it if it is.
Forney sits east of Dallas along US 80, and much of its housing is subdivision construction where whole streets were roofed around the same time with similar shingles. That matters after hail, because whole streets also get inspected, claimed and replaced around the same time. This guide walks the full path, from the storm to a finished roof, so you know what each step should look like before anyone asks you to sign.
Who replaces hail-damaged roofs in Forney, and how do you judge them?
Many roofers will work in Forney after a storm. Some are established North Texas companies. Some arrive with the hail and leave with it. No article can responsibly rank them for you, but you can judge any of them with the same short list:
- A fixed address you can verify, and a phone number that a person answers.
- Memberships you can look up yourself, such as the North Texas Roofing Contractors Association or the Roofing Contractors Association of Texas. Texas has no state roofing license, so these voluntary checks carry more weight; see does Texas license roofers.
- An inspection with photos before any talk of a contract. You should see the damage, slope by slope.
- A straight answer on repair versus replacement.
- Correct insurance language. The roofer documents and estimates. You deal with your insurer.
Verde Roofing is one option that fits Forney. It is locally owned and based in Plano, with no branch offices, and Kaufman County is one of the eleven counties on its service area list. The rest of this guide applies no matter whom you call.
Does hail on a Forney roof always mean replacement?
No, and a roofer who says yes before climbing a ladder has told you something about how they work.
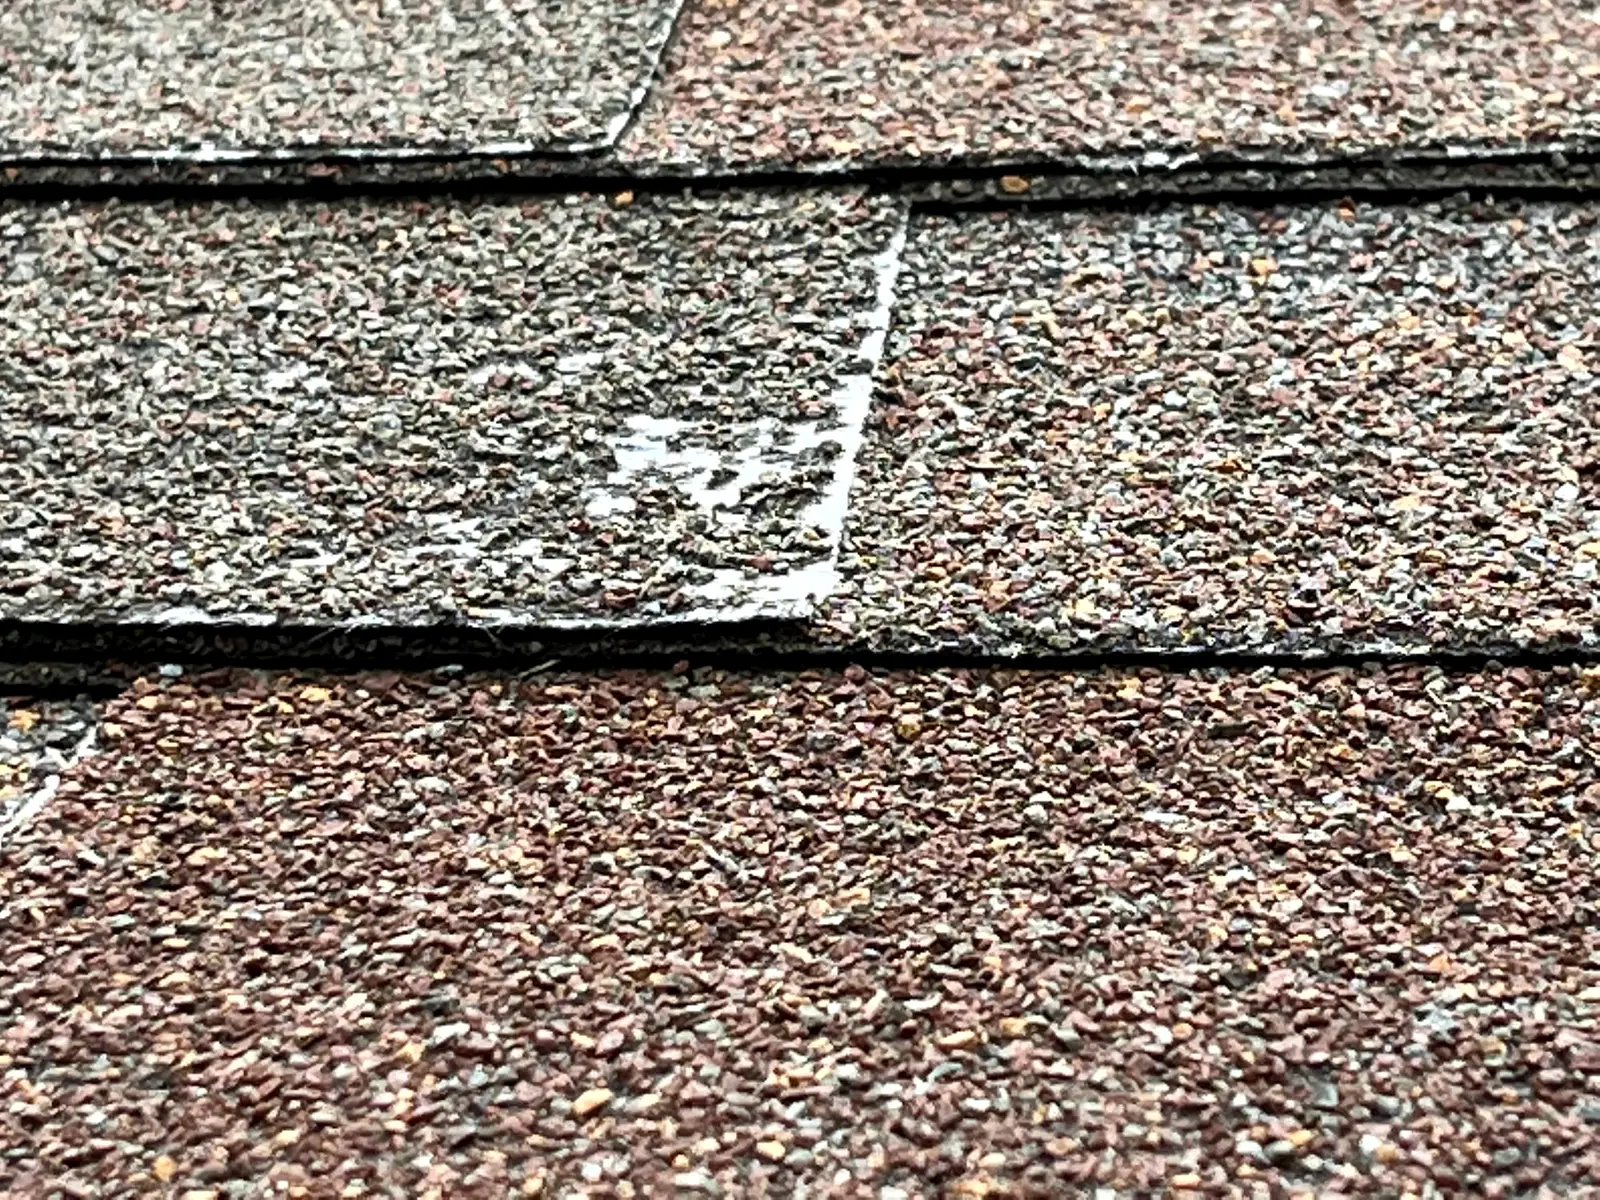
A storm can leave one house with a few bruised shingles on the slope facing the wind, and leave the next house with fractured shingles on every plane. The first is a repair, often cheaper than your deductible. The second is a replacement conversation. In between, the answer depends on how many hits per slope, whether the shingle mat is fractured or only scuffed, and whether a repair can be blended into the existing roof.
You may not need a roofer's ladder at all if the soft metal around the house, such as gutters, downspouts, vent caps and the AC unit's fins, shows no dents. Clean metal usually means the shingles were spared too. Our guide to signs of hail damage on a roof shows what real bruising looks like next to blistering and ordinary wear.
What is the path from hailstorm to finished roof?
People tend to picture one event: "the insurance replaces the roof." It is really a chain of handoffs between you, your insurer and your roofer, and most problems start when someone skips a link.
| Stage | Who does it | What you should have afterward |
|---|---|---|
| Protect the house | You, or a roofer for tarping | Receipts for any temporary repair |
| Roof inspection | Roofer, with you present | Dated photos of every slope and of dented soft metal |
| Decision to file | You | A clear reason to file, or a reason not to |
| Reporting the claim | You | Claim number, adjuster's name and contact |
| Adjuster's inspection | Insurer's adjuster; your roofer may attend | Notes on what was looked at |
| Insurer's estimate | Insurer | Written scope with line items and deductible |
| Contractor's written estimate | Roofer | Line-by-line scope you can set beside the insurer's |
| Build | Roofer | New roof, cleanup, final walk-through |
| Final payment | You and insurer | Proof you paid the deductible; final invoice |
Here is the same path as steps you can follow:
- Stop any water first. If the roof is open, get it covered and keep the receipt. The Texas Department of Insurance (TDI) advises policyholders to prevent further damage and keep receipts for all expenses.
- Get the roof inspected and photographed. Ask for the photos. They are your record whether or not you file.
- Read your policy. Find the wind and hail deductible, whether the roof is covered at replacement cost or actual cash value, and the deadline for reporting a claim.
- Decide whether to file, then report the claim yourself. The call comes from you, not from a contractor.
- Be home for the adjuster. TDI's advice is to be available so you can point out damage. Your roofer can be there to show what the inspection found.
- Compare the insurer's scope with the roofer's written estimate. Differences in measurements or missing items are questions for you to raise with your insurer.
- Choose materials and get any HOA approval. Do this before the order is placed.
- Schedule the build, then close out. Pay your deductible, keep proof, and send the final invoice to your insurer if depreciation was held back.
For more depth on each link, read how a roof insurance claim works in Texas and what to expect from the adjuster's roof inspection.
How fast does the insurance company have to move?
After a storm that hits a whole city, the wait feels endless, so it helps to know the legal clock. According to TDI, your insurer has 15 business days to acknowledge your claim, and then 15 business days to accept or reject it after it has everything it asked you for. It can extend that deadline by 45 days if it tells you why, and TDI can add 15 days after a weather-related catastrophe. Once the insurer agrees to pay, it must pay within five business days.
TDI also notes that if you have a home loan, the payment usually goes to your mortgage company, and you then work with that company to release the money for repairs. That extra step catches many owners by surprise. Call your loan servicer early and ask how it releases claim funds.
What will you pay out of pocket?
Your deductible, plus any upgrades you choose. That is the honest answer for a covered replacement.
Many Texas policies carry a separate wind and hail deductible written as a percentage. The Texas Office of Public Insurance Counsel explains that the percentage is calculated on the amount of insurance on your home, not the size of the claim, and gives this example: on a home insured for $200,000, a 1% deductible is $2,000 and a 3% deductible is $6,000. Do that math with your own declarations page before the adjuster arrives.
No roofer can make that number disappear. Texas Business and Commerce Code §27.02 makes it a Class B misdemeanor for a contractor paid from insurance proceeds to pay, waive, absorb or rebate the deductible, or otherwise help you avoid it, without the insurer's consent. The same section requires contracts of $1,000 or more on insurance jobs to carry a notice, in at least 12-point bold type, that you must pay your deductible. Our guide to your roof deductible under Texas law covers the details.
If you are paying without insurance, published national figures give a sense of scale. Fixr's 2026 roof replacement guide puts most projects between $7,500 and $14,000, with a range of $3.75 to $11 per square foot depending on material, about $50 per roofing square for tear-off and $2 to $8 per square foot for any decking that has to be replaced. Those are national ranges, not Verde's prices. Roof size, pitch, the number of stories and the shingle line you pick move the figure most; the roof cost calculator lets you test the variables.
What belongs on the scope for a subdivision home?
Production-built neighborhoods share some traits that should show up in the written scope:
- Full tear-off and decking check. The estimate should say what happens, and at what price per sheet, if damaged decking is found.
- Every roof accessory listed. Pipe boots, vents, ridge cap, starter, drip edge and flashing, each marked new or reused.
- Soft metal and the rest of the exterior. Hail that damaged shingles usually marked gutters, window screens and fence caps too. Those belong in the same inspection; see roof and exterior storm damage repair from one contractor.
- HOA approval. Many planned communities require approval of shingle style and color. Read your covenants and submit early.
- Permit. Ask the roofer to confirm with the City of Forney's building department whether your job needs a permit and who pulls it. Do not accept "nobody checks."
- Upgrade lines kept separate. If you want an impact-rated shingle, it should be its own line so the insurance scope stays clean. Our guide to Class 4 shingles explains what the rating means.
Which mistakes cost Forney homeowners the most after hail?
Signing at the door. A form presented as "permission to inspect" can be a contract that commits you to that company if the claim is approved. Read every page, and never sign anything with blanks, which TDI specifically warns against.
Letting a contractor run the claim. TDI states that Texas does not allow a roofer or contractor to act as a public insurance adjuster on a job where it is also doing the work, or to advertise that it will. A salesperson who promises to deal with your insurer for you is promising something the law bars.
Taking the "free roof." Any version of "you will not pay your deductible" is the offense described above. TDI directs consumers to report it to the Texas Attorney General at 800-621-0508.
Paying in full up front. TDI's guidance is not to pay in full before the work is done.
Waiting a season. Policies set their own reporting deadlines, and small leaks from fractured shingles get worse. Our guide to storm chasers lists more warning signs.
How does Verde approach a hail replacement in Forney?
Owner Chris Grimes inspects the roof with you and photographs what he finds. Before any claim is filed, he explains whether he sees a repair or a replacement, so you can decide with the evidence in front of you. If you file, the claim is yours: Verde documents the damage, meets your adjuster on site to show what the inspection found, writes the estimate and explains the process and forms. Verde does not act as a public adjuster.
When I walk a roof after hail, I start with the soft metal, because vents and gutters record the size of the stones more honestly than shingles do. Then I photograph each slope so the homeowner and the adjuster are looking at the same thing.
Replacements are done with Malarkey or Owens Corning shingles, or the material the roof already uses. Verde is an NTRCA Accredited Member and an RCAT member, was voted Best Roofer in the Dallas Observer's Best of Dallas readers' choice in 2021, 2022 and 2023, and holds a 5.0 rating from 54 Google reviews. Ask Verde, like any roofer, for the manufacturer and workmanship warranties in writing. More detail is on the storm and hail damage page.
Start with photos of your own roof
Before you decide anything about a claim, find out what the hail did. Call or text (214) 687-1951, 24/7, or book a free roof inspection. Chris will inspect the roof with you, show you the photos and give you a written estimate if work is needed.
Questions people ask next
My Forney house is only a few years old. Can hail really total a roof that new?
Yes. Hail does not care about age; what matters is the size and hardness of the stones and how many hits each slope took. A newer roof often has more granules and a more flexible mat, so it may fare better than an older one on the same street, but the only way to know is an inspection with close-up photos of each slope.
Does my builder's or shingle manufacturer's warranty cover hail damage?
Usually not. Builder and manufacturer warranties generally address workmanship and product defects, while storm damage is an insurance matter. Read both documents to be sure, and ask whether a replacement affects any remaining builder coverage. If the roofer finds installation defects during the inspection, ask for photos, because that is a separate conversation with your builder.
Verde is in Plano. Will a Plano roofer really come out to Forney?
Verde lists Kaufman County, where Forney sits, among the eleven counties it serves, and it has one office, in Plano. What matters more than the mailing address is whether the company has a fixed North Texas location you can verify, checkable credentials, and whether the person who inspected your roof still answers the phone after the job.
Can I upgrade to impact-resistant shingles when insurance is paying?
You can usually choose a better shingle and pay the difference yourself, because a policy pays to restore what you had. Ask the roofer to show the upgrade as a separate line on the estimate, and ask your agent whether a Class 4 roof earns a premium discount with your insurer before deciding.
Half my street is getting new roofs. Should I file a claim too?
Not because the neighbors did. Hail swaths are uneven, and one side of a street can be hit harder than the other. Have your own roof inspected first. If the damage is minor or would cost less than your deductible, a claim pays nothing. If it is spread across slopes, you will have photos to support filing.
Sources
- Texas Department of Insurance: Getting your insurance claim paid
- Texas Department of Insurance: Roofing and insurance, know the law
- Texas Business and Commerce Code §27.02
- Texas Office of Public Insurance Counsel: Decoding residential property deductibles
- Fixr: How much does a roof replacement cost? (2026)
- Texas Insurance Code §4102.163: Certain contractor business prohibited
Chris Grimes owns Verde Roofing in Plano, Texas, a locally owned residential and commercial roofer serving Dallas–Fort Worth. Verde is an NTRCA Accredited Member, an RCAT member and a Dallas Observer Best of Dallas Best Roofer winner (readers’ choice) in 2021, 2022 and 2023.
Keep reading
Related guides
 Insurance claimsHow a Roof Insurance Claim Works in Texas, Step by StepA Texas roof claim runs in order: protect the home, get the roof inspected and documented, report the claim, meet the adjuster, receive the insurer's decision…Read the guide
 Insurance claimsThe Insurance Adjuster's Roof Inspection: What to Expect and How to PrepareThe adjuster walks the roof, counts hail hits in test areas, checks soft metals, slopes and interior damage, measures the roof and writes an estimate. You…Read the guide
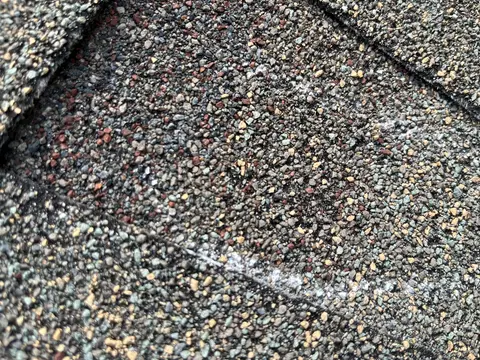 Roofers by cityHail Damage Roof Repair in Rowlett: Who to CallVerde Roofing, a locally owned roofer based in Plano, repairs hail-damaged roofs in Rowlett. Owner Chris Grimes inspects the roof with you, photographs what he finds…Read the guide